Buying an existing business runs in seven steps, and the structure you pick in step one decides which of the seller’s liabilities become yours. A signed letter of intent starts the clock, and most mistakes are locked in before due diligence begins.
KEW Legal® works the deal table on business acquisition closings across Florida.
Two decisions matter most. The first is asset purchase or equity purchase. The second is whether the earnings used to value the business are documented.
Planning to buy a business in Florida? Talk with KEW Legal before you sign a letter of intent.
Key Takeaways
- Structure decides liability: An asset purchase lets you choose which liabilities you assume, while an equity purchase brings every known and unknown liability inside the entity.
- Documented earnings set the price: Businesses sell on a multiple of SDE or EBITDA, and every add-back the seller cannot prove on paper comes straight off the value.
- Florida protections belong in the contract: Hold back purchase money under Fla. Stat. § 212.10 until DOR clearance, and make landlord, license and franchisor approvals conditions to closing.
How Does Buying An Existing Business Work?
Buying an existing business runs through seven steps: search, valuation, letter of intent, due diligence, financing, purchase agreement and closing. Financing and third-party approvals set the closing date. The contract does not.
- Search: Sign an NDA (confidentiality agreement) before the seller shares financials. Confirm any broker holds the Florida license required under Fla. Stat. ch. 475.
- Valuation: Your CPA tests the seller’s earnings against tax returns and bank statements.
- Letter of intent: The LOI is usually non-binding on amount and structure. It is binding on confidentiality, exclusivity and expenses, so we read those clauses first.
- Due diligence: This is verifying what the seller told you. It typically runs 30 to 60 days, and we run the legal side.
- Financing: You supply financials and lender documents. The lender’s conditions run in parallel with diligence.
- Purchase agreement: We draft it and negotiate it with the seller’s counsel.
- Closing: Funds move only after approvals, lien releases and tax clearance are in hand.
Asset Purchase Versus Equity Purchase In Florida
In an asset purchase you choose the assets and liabilities you take. In an equity purchase you buy the entity and every known and unknown liability inside it, meaning membership interests in an LLC under Fla. Stat. ch. 605 or stock in a corporation under ch. 607.
An asset purchase fits a restaurant with a lease and a liquor license. An equity purchase can fit a licensed practice where the entity holds the permit. If an asset purchase needs too many consents, consider an equity purchase and cover the added risk with indemnity and escrow.
The trade is liability control and a tax basis step-up against consents, sales tax on equipment and paperwork. Our notes on choosing a deal structure go further on mixed cases.
| Factor | Asset purchase | Equity purchase |
|---|---|---|
| What you get | Chosen assets and goodwill | The entity and all it owns |
| Inherited liabilities | Only those assumed, plus four exceptions | All known and unknown liabilities |
| Third-party consents | Lease, licenses, contracts often need consent | Fewer; check change-of-control clauses |
| Tax basis | Stepped-up basis in assets | Generally carries over; step-up needs election |
| Sales tax on equipment | Applies to equipment allocation | Generally none; entity keeps assets |
| Speed and paperwork | More assignments and filings | Faster transfer; deeper diligence needed |
Figure 1: An asset purchase limits inherited liabilities. An equity purchase moves faster but carries everything. Source: Amjad Munim, M.D., P.A. v. Azar, 648 So. 2d 145 (Fla. 4th DCA 1994); Fla. Stat. § 212.10.
How Is An Existing Business Valued?
An existing business is valued as a multiple of its earnings, not its revenue.
Here is an illustrative example. Business A has $1,000,000 in revenue and 15% owner earnings, so SDE is $150,000. At an assumed 2.5x, the value is $375,000.
Business B has $300,000 in SDE. At the same assumed 2.5x, it is worth $750,000.
The 2.5x multiple is an assumption for arithmetic, not a market figure. The example shows why “$1,000,000 in sales” says little, and why “$300,000 a year” in documented earnings carries a business.
SDE Versus EBITDA For Small Businesses
SDE (seller’s discretionary earnings) is profit plus owner pay and documented add-backs. It is used for owner-operated businesses. EBITDA is earnings after paying a manager at market rate, and it is used for larger businesses.
Add-backs are expenses the owner pays that a buyer would not. Use SDE if you will run the business yourself. Use EBITDA if you will hire a manager.
Is 3x Profit The Right Multiple?
No. No single multiple fits every deal, because it depends on SDE versus EBITDA, size, owner dependence and industry.
Your CPA or broker can pull current ranges by industry from transaction databases such as DealStats or BizComps. Two facts move the multiple most: how much revenue depends on the owner, and customer concentration.
How Do Add-Backs Change Value?
Every add-back you cannot document comes straight out of the value. A $60,000 undocumented “personal expense” add-back at 2.5x cuts the value by $150,000.
The test is paper: tax returns, bank statements and receipts. If an add-back is not on paper, renegotiate the amount or walk. Do the same if revenue depends on the owner, one customer dominates sales, or diligence turns up unrecorded liabilities.
What Financing Works For Buying A Business?
Most change-of-ownership deals combine an SBA 7(a) loan, a seller note and buyer cash. Retirement-funded structures and partner capital fill the gaps. Our page on how acquisition financing is structured covers the layering in more depth.
There are four common sources:
- SBA 7(a): SOP 50 10 8 requires an equity injection of at least 10% of project costs for a change of ownership. A seller note on full standby for the life of the loan may cover up to half of it. The loan cap is $5 million. Every owner must meet SBA’s citizenship and residency rules, which SBA has revised recently, so we check the current SOP or its successor against the lender’s checklist.
- ROBS: This rolls retirement funds into a C corporation that buys the business. It carries IRS and ERISA compliance requirements and is not a shortcut.
- Seller note: The seller finances part of the purchase amount. The mechanics sit in the purchase agreement.
- Partner capital: An investor contributes equity in exchange for ownership.
“No money down” in practice means one of three things: a large seller note, an earn-out (part of the purchase amount paid later if the business hits targets) or partner capital.
In a typical matter, the timeline runs as follows:
- Search and NDA: This step is set by you and the market.
- Valuation: It takes 2 to 4 weeks once the seller’s records arrive.
- LOI: It takes 1 to 2 weeks to negotiate.
- Due diligence: It takes 30 to 60 days.
- Financing: It runs in parallel with diligence, on the lender’s schedule.
- Closing: It follows the last approval.
Which Florida Liabilities Follow The Buyer?
In an asset purchase, the buyer generally does not take the seller’s debts. Four exceptions and one Florida tax statute can still put them on you.
In an equity purchase, every liability stays inside the entity you now own. In either structure, the contract tools are the same: an excluded-liabilities clause, indemnity from the seller and a holdback from the purchase money.
Our legal due diligence work finds what those tools need to cover. If the seller’s tax status is unclear, extend the holdback and delay release until clearance arrives.
Successor Liability Exceptions In Asset Sales
Amjad Munim, M.D., P.A. v. Azar, 648 So. 2d 145 (Fla. 4th DCA 1994), recognizes four exceptions: assumption, de facto merger, mere continuation and fraudulent transfer.
- Express or implied assumption: You agree to the debt in writing or by conduct.
- De facto merger: The same owners run the same operation, and the seller receives thin payment.
- Mere continuation: The new business is the old one under the same name and control.
- Fraudulent transfer: The sale strips assets away from creditors.
Section 212.10 Sales Tax Withholding
Under Fla. Stat. § 212.10, the buyer must withhold enough of the purchase money to cover the seller’s unpaid sales tax or become personally liable for it. You withhold until the Department of Revenue shows the tax is paid or that none is due.
The seller’s final return is due within 15 days of the sale. We tie holdback release to the DOR receipt or certificate.
Closing Checklist For Seller Debts
Run five checks before funds move: DOR tax clearance, reemployment tax status, a UCC lien search, a judgment search and a holdback or escrow. UCC searches go through the Florida Secured Transaction Registry. In an equity purchase, also confirm entity status on Sunbiz.
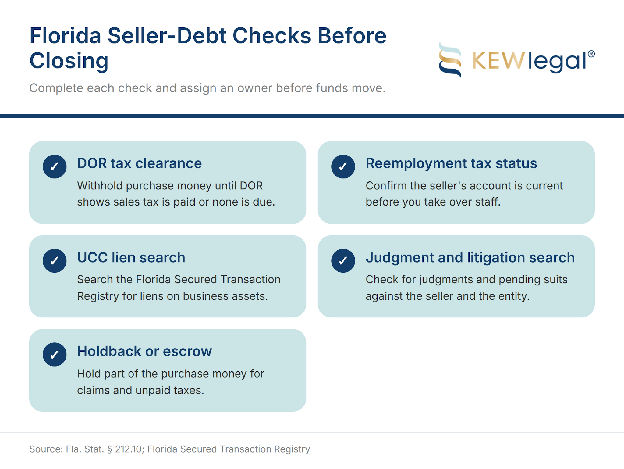
Figure 2: Five checks keep the seller’s tax and lien problems from becoming yours. Source: Fla. Stat. § 212.10; Florida Secured Transaction Registry.
Assign each check to a person and a date. We run the searches. You send the seller’s debt schedule.
Which Approvals Can Stop A Signed Deal?
Four third parties can stall a signed deal: the landlord, the licensing agency, the franchisor and counterparties with anti-assignment clauses.
- Landlord: Most commercial lease assignments need landlord consent. The landlord may also demand a new personal guaranty from you.
- Licensing agency: DBPR alcohol licenses, AHCA or DOH health care licensure, and local business tax receipts under Fla. Stat. ch. 205 need reissue or change-of-ownership approval. They do not transfer automatically.
- Franchisor: The franchisor must approve the transfer, and transfer charges apply.
- Counterparties: Customer contracts and key-employee agreements may bar assignment.
We handle commercial lease assignments and franchise transfer approvals as part of the deal, and the franchise process starts when the LOI is signed. Make lease and license approval a condition to closing, and ask each agency for its current lead time at the LOI stage.
What Belongs In The Purchase Agreement?
The purchase agreement fixes what you buy, what you assume and what the seller must make good if the disclosures prove false. It has four core parts:
- Representations and warranties: These are the seller’s statements about financials, taxes, litigation, contracts and employees.
- Indemnity: This sets a basket (the minimum claim), a cap and a survival period. An escrow or holdback backs it.
- Closing conditions: These include landlord and license approvals, lien releases and DOR clearance.
- Transition period: The seller trains you and makes introductions for a stated number of days.
How Does Allocation Affect Taxes?
In an asset deal, the purchase amount is split across asset classes, and the split sets your tax result. Both sides report it on IRS Form 8594 under IRC § 1060.
Take a hypothetical $600,000 deal. It splits into $60,000 of inventory, $120,000 of equipment, a $20,000 non-compete and $400,000 of goodwill.
Goodwill and the non-compete amortize over 15 years under IRC § 197. Qualifying used equipment from an unrelated seller can be expensed under 100% bonus depreciation (for property acquired after January 19, 2025) or § 179.
Florida sales tax applies to the $120,000 of equipment. That comes to $7,200 at the 6% state rate, plus the county surtax.
Goodwill is not taxed, and inventory bought for resale is exempt with a resale certificate. Buyer and seller have opposing tax interests, so negotiate the allocation before signing.
Seller Non-Compete And Seller Note Terms
Under Fla. Stat. § 542.335(1)(d), a seller’s restraint of 3 years or less is presumed reasonable, and more than 7 years is presumed unreasonable. For employees, the presumptions are 6 months and 2 years.
The FTC non-compete rule was set aside in 2024, and its sale-of-business exception was never at issue.
Here is an illustrative seller note: $400,000 at 6% over 5 years comes to about $7,733 a month. Add an offset clause so indemnity claims reduce note payments.
The seller’s security interest and any SBA standby terms limit when payments can be made. Florida documentary stamp tax on the non-mortgage note is $0.35 per $100, which is $1,400 on $400,000, subject to the cap in § 201.08.
Which Documents Close The Deal?
An asset closing needs five documents: a bill of sale, an assignment and assumption agreement, the lease assignment with landlord consent, lien releases and DOR confirmation.
After closing, an asset buyer gets a new EIN. An equity deal needs a Sunbiz amendment.
Both need a reissued business tax receipt. File Form 8594 with your tax return and send notices to customers and vendors.
Send Us The Letter Of Intent Before Signing
KEW Legal® sits at the deal table for founders and investors. Our founder, Kristina E. Wilson, was Associate/Deputy General Counsel at Trump Dezer Development, so we read your draft the way the seller’s counsel will.
Send the draft LOI, three years of tax returns, the lease, the license list and the seller’s debt schedule to our M&A team. We stay on the matter through closing and follow-through.
Schedule a consultation about your closing, and include your LOI deadline date in the request.